

BILL Spend & Expense (Divvy)
by Bill.com Inc.
4.5
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 4.5
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
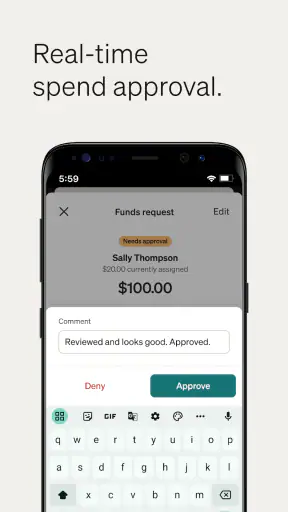
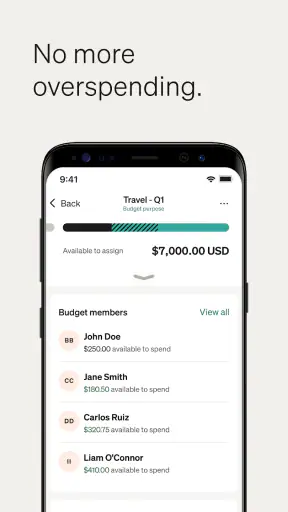
 Analysis by Getfullapps
I look at business finance apps differently from ordinary productivity tools. A budgeting app can be inconvenient and still be harmless; a corporate spending app sits much closer to company money, employee purchases, approvals, and financial records. That makes trust, account control, and clear user choices just as important as speed. After spending time with BILL Spend & Expense, I see it as a focused business app for organizations that want corporate cards and expense management in one place, rather than another general-purpose wallet or receipt scanner.
The app is developed by Bill.com Inc. and is available free of charge with an Everyone content rating. It belongs firmly in the business category, and its purpose is easy to understand: help a company manage spending while giving employees a practical way to handle work purchases. The current version is 4.0.17, and it requires operating system version 12 or later. That last point matters before anyone on an older phone invests time in setting it up.
Its public reception is encouraging without making it look universally perfect. BILL Spend & Expense holds a 4.5 average from around 4.3 thousand ratings, with more than 500 reviews and over 100 thousand installs. I would treat that as a useful sign of adoption, not as proof that every company will have the same experience. A finance workflow depends heavily on how an organization configures spending rules, who approves purchases, and how carefully employees use the app.
How trust is built around company spending
I find trust in a company spending app is built less by a reassuring first impression than by whether people understand the process around it. I would begin with a small, ordinary purchase and check that the employee, reviewer, and finance team each know what they need to do with the record. That practical test also helps reveal where sensitive details need a clearer handling rule.
A business tool rather than a personal finance substitute
The first thing I would clarify to a friend is that this is not designed to replace a personal banking app. Its value appears when several people spend on behalf of one organization and the business needs a consistent way to oversee those purchases. Corporate cards and expense management are connected here, so the app makes more sense for a team than for an individual trying to track household expenses.
That distinction changes how I judge it. I am not primarily looking for investment charts, bill reminders, or personal savings advice. I am looking for a clean relationship between a work purchase, the person responsible for it, the company’s rules, and the eventual expense record. When those links are handled well, employees spend less time explaining ordinary purchases and finance teams spend less time chasing missing details.
The developer name is visible and straightforward, which is useful in a category where users should know who operates the service before connecting business activity to it. I also appreciate that the app presents itself as a specialized business product instead of pretending to be an all-in-one financial solution. That narrower identity makes it easier to decide whether it belongs in a company’s workflow.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What the app changes in a normal workday
Imagine a sales employee traveling for a client meeting. They use the company card for transportation, a meal, and a small presentation expense. Without a dedicated process, the employee may keep paper receipts, forward several emails, and later try to remember which purchase belonged to which meeting. A corporate card and expense app can bring those tasks into a single routine, letting the employee deal with the purchase while it is still fresh instead of reconstructing the trip at the end of the month.
For a manager, the benefit is not simply seeing that money was spent. The more useful question is whether the expense can be understood and handled according to company policy. For finance staff, the goal is a cleaner trail from spending to review. This is where BILL Spend & Expense feels more purposeful than a generic notes app, spreadsheet, or personal receipt organizer.
There is a trade-off, though. A shared business workflow only becomes trustworthy when everyone follows it. If employees continue using personal cards, save receipts in random places, or delay recording purchases, the app cannot magically repair the process. I would introduce it alongside a clear internal rule about when to use the corporate card and when to document an expense.
Controls matter more than a polished dashboard
My strongest positive impression is that the product’s usefulness depends on control rather than decoration. A finance app should help a company decide who can spend, how purchases are reviewed, and what information is attached to an expense. Those controls are more valuable than a visually impressive home screen because they shape what happens after the purchase.
In practice, I would want the person responsible for the account to establish the workflow before inviting a whole team. Decide which employees need spending access, who reviews their expenses, and what supporting details are expected. That preparation is one of the less obvious requirements of adopting a corporate spending tool. The app can organize a process, but it cannot decide the company’s policy for it.
I also see a useful separation between the employee’s immediate task and the organization’s oversight. An employee needs a quick way to deal with a work purchase; a manager needs enough context to review it; finance needs records that can be reconciled later. If one screen tries to serve all three audiences equally, the experience can become confusing. A successful rollout should therefore explain each person’s responsibility instead of assuming the interface will do all the teaching.
Where user agency becomes important
Corporate spending creates an unavoidable power difference: the organization controls the account, while employees may be the people entering purchase information. That makes visible choices especially important. Before using the app, I would explain to employees what they are expected to submit, who can review the information, and how corrections should be handled. Clear internal communication is part of responsible use, not an optional extra.
For administrators, the practical agency comes from setting boundaries before spending happens. A team should not discover its approval expectations only after a disputed transaction appears. I would test the process with a small group first, use an ordinary work purchase, and check whether the resulting record is understandable to both the employee and the reviewer. That trial can reveal confusing steps without putting the whole organization through a difficult launch.
For employees, the best workflow is one that can be completed immediately after a purchase. Waiting until the end of a trip increases the chance of forgotten context, misplaced receipts, and vague descriptions. My advice would be to treat the app as part of the purchase routine, not as a monthly administrative chore. That small habit is likely to matter more than any individual convenience feature.
Data-sensitive moments and practical limits
When a purchase involves business information, I prefer to make a deliberate pause part of the routine rather than rely on assumptions. I would check who is expected to provide context, who will review it, and whether the device is appropriate for work use before putting the workflow into regular service. Those limits are worth considering alongside the app’s convenience, especially when a company is deciding whether the setup fits its team.
Why finance information deserves deliberate handling
Any app connected to corporate spending deserves a more careful setup than a casual download. A user may enter or encounter transaction details, work-related descriptions, receipts, and information about business activity. I would avoid installing it on a shared device, use a device lock, and keep the operating system supported. Those are ordinary precautions, but they become more important when an app sits inside a company’s financial process.
I would also separate personal and work accounts wherever the organization allows it. Mixing identities can make it harder to understand who should see an expense and which account owns the record. Before onboarding, an administrator should confirm the company’s chosen account structure and make sure employees know whether they are using an individual work login or another managed arrangement.
My cautious approach is not a claim about hidden behavior. It is simply good practice for a tool handling sensitive business activity. I would read the app’s current privacy and account documentation during setup, review the access choices shown on the device, and avoid granting anything that is not needed for the intended workflow. If a prompt is unclear, I would pause and ask the company administrator rather than accepting it automatically.
When the app is likely to be a good fit
I think BILL Spend & Expense is most suitable for a small or growing organization that has outgrown informal expense collection but does not want employees juggling a corporate card system and a separate expense app. It can also make sense for distributed teams, where a shared process is harder to maintain through paper receipts or scattered email threads.
The strongest use case is a company with recurring employee purchases and a real need for review. Travel, client meetings, supplies, subscriptions, and field work all create situations where a purchase needs context after the card is used. Bringing those expenses into one business-oriented workflow can reduce the memory burden on employees and make review more consistent.
I would be less enthusiastic for a solo freelancer who makes very few business purchases. That person may find a simple spreadsheet, bank export, or accounting application more flexible and less dependent on an organizational setup. Likewise, a large company with highly specialized procurement, accounting, or enterprise identity requirements should test the complete workflow before committing. A focused app can be easier to use, but it may not cover every complex process a mature finance department already relies on.
How it compares with familiar alternatives
The usual alternative is a spreadsheet. A spreadsheet is inexpensive, adaptable, and familiar, but it depends on employees remembering to update it and on someone checking the entries manually. It can work for a very small team, yet it becomes fragile when several people submit expenses in different formats. BILL Spend & Expense is more purpose-built for the relationship between corporate spending and expense review.
Another alternative is using a corporate card provider for transactions and a separate receipt or accounting tool afterward. That arrangement may be better for a company that already has a mature accounting stack and wants specialized tools for each stage. The drawback is the handoff: employees and finance staff may need to move information between systems, and small mismatches can create extra work.
Personal finance apps are a poor comparison for most teams. They are generally designed around one person’s money, not shared business responsibility. BILL Spend & Expense is more relevant when the question is not merely “where did the money go?” but “who spent it for work, what was it for, and how should the organization handle it?” That is a narrower job, but it is the reason to choose this kind of product.
Three workflow lessons I would apply immediately
- Start with a controlled pilot: give the app to a small group with ordinary purchases before expanding access. This exposes unclear responsibilities and confusing approval habits while changes are still easy.
- Record context at the moment of purchase: a short, specific explanation written immediately is more useful than a vague note added weeks later. Employees should make this part of their normal card routine.
- Review access as roles change: when someone changes teams or no longer needs business spending access, the organization should include account review in its offboarding and role-change checklist.
A fourth lesson is to distinguish a missing receipt from an unclear business purpose. Those are different problems and should not be treated as interchangeable. A company can have a receipt that proves an amount but still lack enough context to understand why the purchase was made. Training employees to supply both pieces makes the review process more meaningful.
Questions I would settle before adoption
A prospective user will probably wonder whether the app is suitable for their phone. The practical answer is to check the operating system first: version 12 or newer is required. If a company has older devices in circulation, that should be part of the rollout plan rather than discovered when an employee is traveling.
Another natural question is whether the free price makes it a personal finance tool. I would not assume that. The app is free to download, but its usefulness depends on an organization’s account structure, corporate cards, spending rules, and internal process. A person should confirm how their employer intends to use it before treating the app as an independent expense solution.
People may also ask whether it can replace accounting software. I would be careful here. Its clear focus is corporate cards and expense management, while accounting may involve broader records, reporting, tax work, and reconciliation needs. It may sit alongside an accounting workflow rather than eliminate every other finance system.
Finally, a manager may ask whether installing the app alone will improve control. In my view, no. The real improvement comes from pairing the app with defined responsibilities, timely submissions, careful access management, and a review habit. The software can make those practices easier to follow, but it cannot substitute for them.
My cautious verdict
I would recommend BILL Spend & Expense to a business that wants a dedicated home for corporate card activity and employee expenses, especially when the current process relies on scattered receipts, email, or a spreadsheet that several people edit differently. The app’s business focus is its main strength. It gives a team a more natural place to handle work purchases than a personal finance application ever could.
I would not recommend adopting it casually or assuming that a free app removes the need for planning. Before rollout, I would confirm device compatibility, define who can spend and review, explain what employees should record, and inspect the account and privacy choices shown during setup. Those steps protect user agency and help the company understand what information is entering the workflow.
My final view is positive but measured. The 4.5 average and growing install base suggest that many users find value in the approach, while the product’s focused purpose makes its audience clear. For a team with recurring business expenses, it can replace a surprisingly messy collection of habits with a more coherent routine. For a solo user, an older-device owner, or a company needing a deeply specialized finance ecosystem, a simpler or more comprehensive alternative may be the better choice.
If I were recommending it to a friend, I would say this: choose it when your real problem is shared business spending and expense follow-up, not merely personal budgeting. Set the rules first, test one complete purchase from card use through review, and make sure every person understands their part. Used that way, BILL Spend & Expense is a sensible tool for bringing corporate spending under clearer control without pretending to solve every financial task a business may have.
Pros
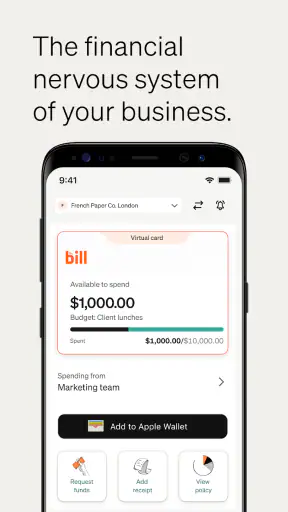
- Real-time spending visibility helps teams monitor budgets as purchases happen.
- Virtual cards can reduce exposure when shared with employees or vendors.
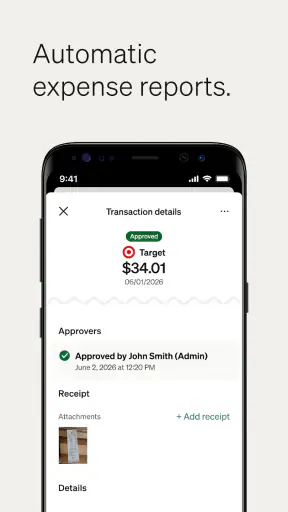
- Receipt capture keeps transaction documentation organized in one place.
- Custom controls help limit spending by merchant, amount, or category.
- Useful reporting tools support expense reviews and budget planning.
Cons
- Some advanced features may require a paid plan or administrator approval.
- Employees may need training to follow approval and receipt workflows.
- Bank or card integrations can occasionally experience syncing delays.
- The app is less useful for individuals without an employer-managed account.
- Strict company policies may decline legitimate purchases unexpectedly.
FAQs for BILL Spend & Expense (Divvy)
What is BILL Spend & Expense (Divvy), and who is it designed for?
BILL Spend & Expense, formerly known as Divvy, is a business spend-management app designed to help companies control employee spending, manage corporate cards, organize budgets, and track expenses. It is mainly intended for businesses and their employees rather than personal finance users. Administrators can create spending limits and approval rules, while employees can use the app to view available funds, make purchases, and submit expense details.
Can employees use the app to submit receipts and manage expenses?
Yes. Employees can generally use BILL Spend & Expense to record business purchases, attach receipts, add notes or expense categories, and submit transactions for review. The app is useful for keeping expense information organized while traveling or working away from a desk. However, the exact options available may depend on the company’s account configuration, assigned permissions, card program, and approval workflow.
Does BILL Spend & Expense provide corporate cards or only expense tracking?
BILL Spend & Expense is more than a basic receipt-tracking tool. Depending on the company’s plan and setup, it can support corporate card spending, virtual cards, budgets, employee allowances, purchase controls, and expense reporting in one system. This means businesses may use it to control spending before a transaction occurs and reconcile activity afterward, although card availability, limits, fees, and eligibility are determined by BILL and the employer.
Is BILL Spend & Expense secure for handling company spending information?
The platform is built for business financial workflows and includes account access controls, transaction monitoring, spending policies, and administrative oversight. These features can help companies reduce unauthorized purchases and maintain a clearer audit trail. Nevertheless, users should protect login credentials, enable available security options, and avoid accessing the account on unsecured devices. Security and privacy also depend on the company’s configuration and BILL’s current policies.
Is BILL Spend & Expense free to download and use?
Downloading the mobile app may be free, but that does not mean the complete service is free for every user. BILL Spend & Expense is generally provided through a business account, and pricing, card costs, plan limits, and included features can vary. Employees normally access the service through their employer’s subscription or invitation. Before relying on the app, businesses should review current pricing, eligibility requirements, and any applicable terms directly with BILL.

BILL Spend & Expense (Divvy)
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via spendsupport@hq.bill.com, visit https://www.bill.com/product/spend-and-expense, or review their https://www.bill.com/privacy.










